Housing market volatility and financialization mechanics interact directly with localized legal frameworks to produce acute systemic displacement. When housing is treated purely as a liquidity instrument rather than a localized public utility, default mechanisms trigger predictable cascade failures among vulnerable populations. The operational mechanics behind residential evictions, debt accumulation, and social unrest reveal a structural failure mode where systemic risk is systematically shifted onto those least equipped to absorb capital shocks.
The Economic Architecture of Residential Default
The forced removal of long-term tenants or homeowners from primary residences is rarely an isolated administrative event. It represents the final step in a multi-stage financial attrition process. To understand how an eviction escalates from a bilateral contract dispute into a civic crisis, one must examine the cost function of residential occupancy versus capital yield expectations.
Assets under management in urban housing markets face constant pressure to maximize yield. When property values appreciate due to speculative influxes, localized tax burdens, refinancing costs, and rental indexes adjust upward. For fixed-income occupants—such as pensioners dependent on statutory state allowances—income elasticity is strictly zero. They cannot scale revenue generation to match inflationary or speculative pressures.
This creates an immediate liquidity squeeze. The structural failure occurs along three specific vectors:
- The Fixed-Income Lag: Statutory pensions adjust annually or semi-annually, lagging behind real-time shifts in property holding costs, municipal levies, and utility tariffs.
- Capital Access Asymmetry: Aging populations face structural barriers to refinancing or credit restructuring, locking them into legacy debt instruments or predatory subprime arrangements when liquidity runs dry.
- Collateralization Friction: Financial institutions holding distressed mortgages or rental properties operate under regulatory mandates that prioritize asset recovery velocity over human capital preservation, transforming temporary cash-flow mismatches into permanent permanent capital destruction for the occupant.
When these vectors converge, the default threshold is crossed. The legal apparatus then initiates execution protocols that treat the domicile strictly as a balance-sheet liability to be cleared.
Systemic Amplification and Protest Dynamics
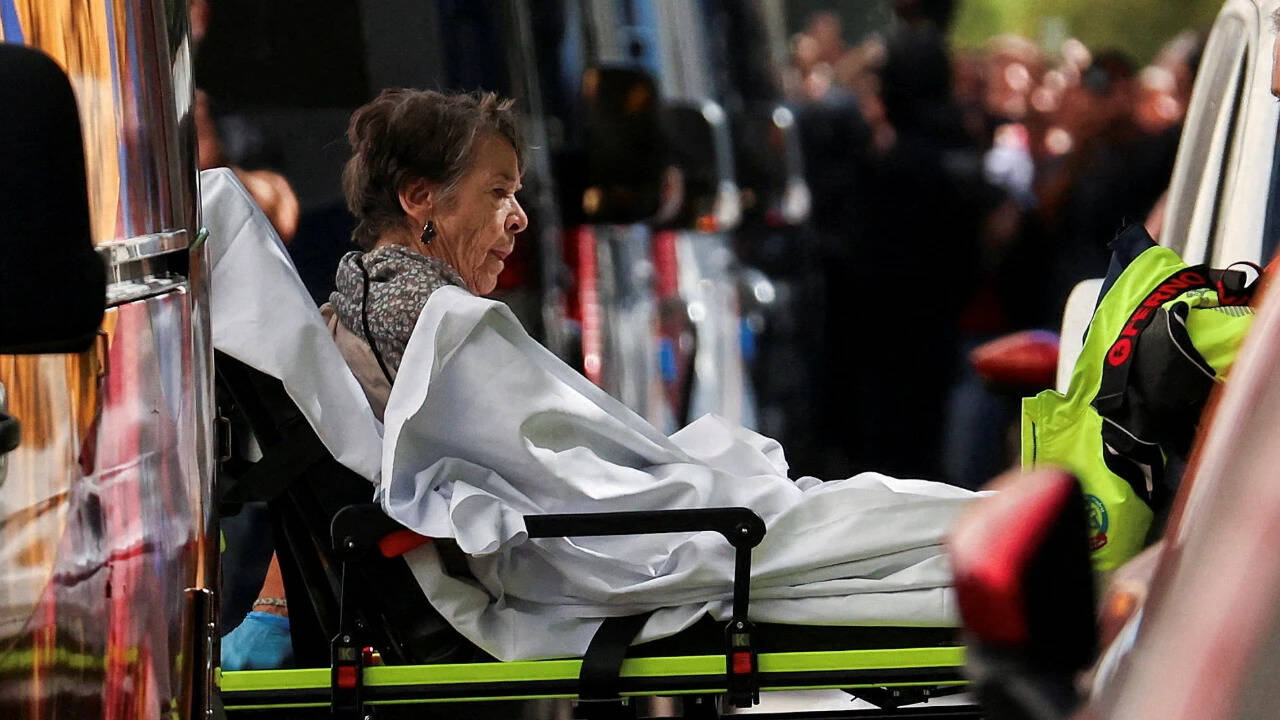
Public resistance to housing displacement operates according to distinct mobilization physics. When an eviction targets an elderly or acutely vulnerable demographic, the transaction cost of enforcement rises sharply for municipal authorities.
The public response observed in high-profile housing disputes stems from perceived systemic injustice. Citizens identify a fundamental misalignment between legal compliance and moral legitimacy. This manifests in specific behavioral patterns:
- Physical Impedance: Community networks deploy localized blockades to disrupt the operational timeline of law enforcement and bailiff agencies, increasing the friction coefficient of execution.
- Institutional Signaling: Protests serve as a high-visibility feedback loop directed at municipal legislatures, forcing political actors to weigh the electoral cost of strict judicial enforcement against the optics of institutional cruelty.
- Media-Mediated Contagion: Visual documentation of institutional displacement accelerates collective outrage, transforming a local civil matter into a macroeconomic debate regarding the social contract of property rights.
However, localized resistance rarely alters the underlying legal framework. Protests act as a temporary circuit breaker. They delay execution but do not modify the balance-sheet calculus driving the displacement wave. Without systemic interventions targeting the root cause—namely, the divergence between wage/pension growth and real estate asset inflation—activism remains reactive rather than structural.
Institutional Failure Points and Regulatory Latency
The regulatory apparatus governing housing security suffers from chronic latency. Legislative bodies typically enact tenant protections or mortgage relief mechanisms only after systemic shocks have materialized. This lag guarantees that relief measures arrive downstream of the primary damage.
Judicial systems enforce contracts based on narrow statutory interpretations, frequently lacking the discretionary mandate to weigh the human capital cost of displacement against the creditor's enforcement rights. This creates an institutional vacuum where neither the market nor the state accounts for the negative externalities of mass evictions.
These externalities include immediate increases in municipal emergency shelter expenditures, accelerated health decline among displaced elders due to environmental shock, and the erosion of social cohesion within urban neighborhoods. When an 87-year-old individual experiences forced displacement, the psychological and physiological trauma frequently precipitates rapid somatic decline, culminating in acute medical emergencies or mortality. This is not an incidental byproduct of the system; it is a predictable cost absorbed entirely by the individual and public healthcare infrastructure, while private capital gains remain insulated from the fallout.
Re-Engineering the Housing Risk Matrix
Mitigating residential displacement requires shifting from reactive humanitarian interventions to structural risk redistribution. Standard market corrections assume liquidity solutions will emerge organically, yet history demonstrates that distressed populations lack the runway for market-driven adjustments.
Sustainable interventions require altering the equation at the point of origin:
- Dynamic Subsidy Indexing: Linking housing allowances and pension adjustments directly to real-time micro-market rental and property tax indices rather than lagging macroeconomic metrics.
- Encumbrance Restrictions: Establishing mandatory mediation windows and debt-restructuring protocols for vulnerable demographics before legal execution can be filed, prioritizing loss-mitigation strategies that preserve primary occupancy.
- Municipal Right of First Refusal: Empowering local housing authorities to acquire distressed primary residences and convert them into permanently affordable community land trusts, thereby breaking the cycle of speculative churn.
Until regulatory frameworks mandate that housing security supersedes short-term capital yield extraction for primary residences, displacement cascades will continue to generate acute social volatility. The structural mechanics are clear; altering the outcome requires rewriting the underlying risk-allocation rules.