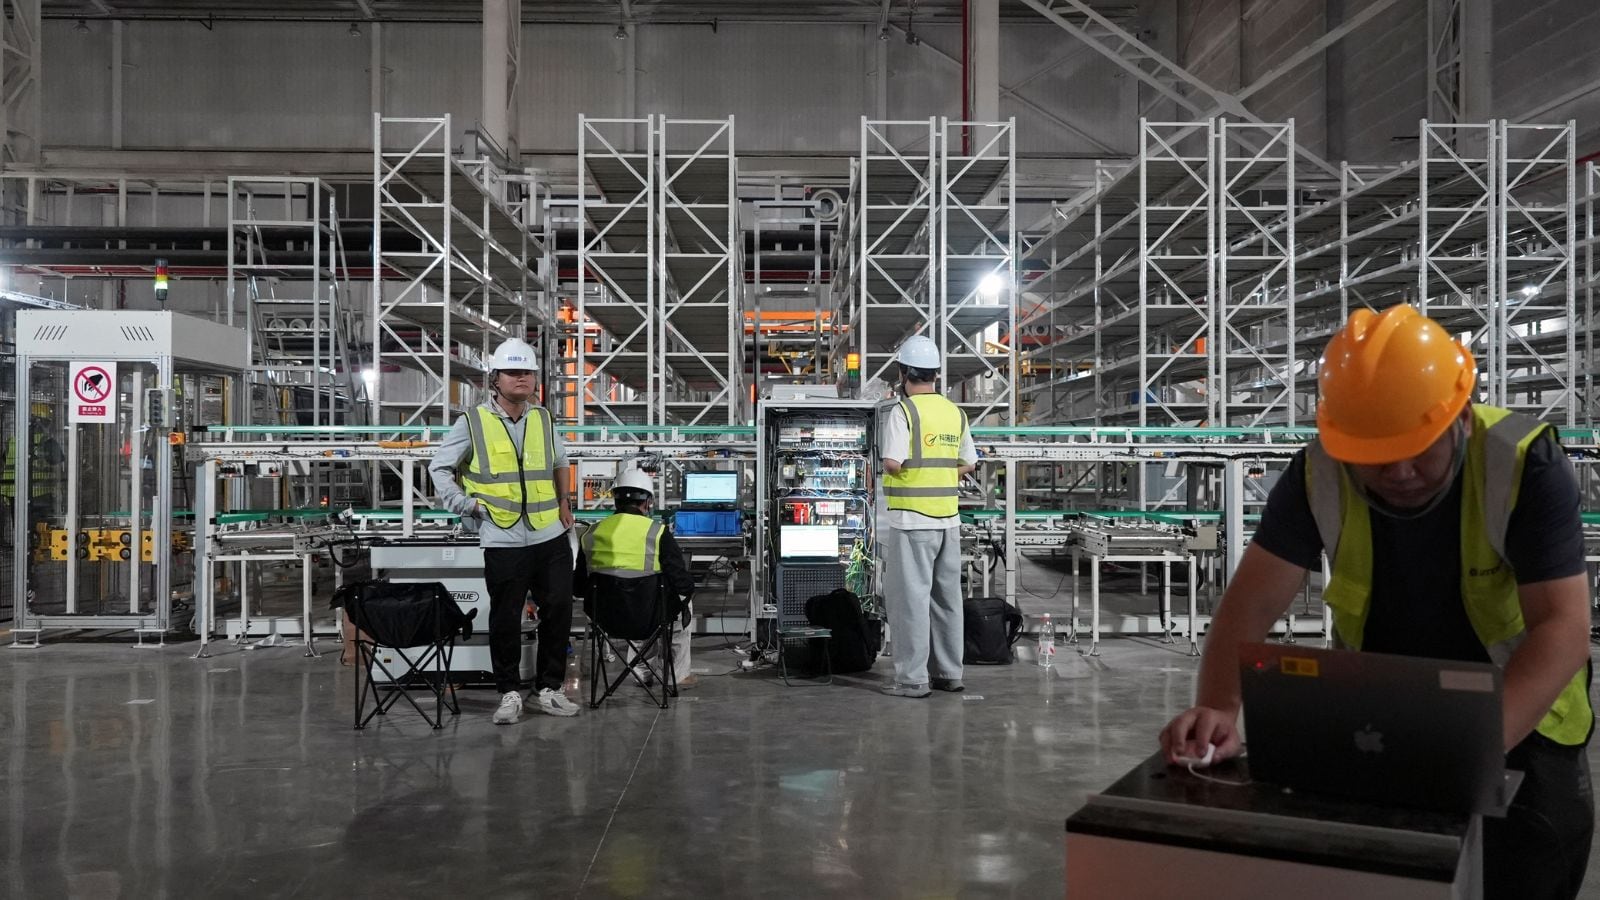
China industrial profit growth decelerated sharply to 4.2 percent year-on-year in August, marking the slowest monthly expansion pace of the year and laying bare a structural fracture that standard macroeconomic tracking consistently misses. Official figures from the National Bureau of Statistics show that while high-tech manufacturing and automated electronics continue to churn out high-value hardware fueled by global artificial intelligence investments, the broader domestic manufacturing ecosystem is bleeding pricing power. This isn't merely a story of cooling demand; it is a profound operational mismatch between what Chinese factories are built to produce and what domestic balance sheets can actually absorb.
For years, industrial policy prioritized physical output and capacity expansion above asset efficiency or consumer returns. Factories received state-backed credit to scale up production lines long before end-market absorption curves justified the capital expenditure. By August, that strategy hit a mathematical wall. Cumulative industrial profits for the first eight months of the year still showed an apparent expansion of 15.7 percent, largely buoyed by robust performances earlier in the calendar and localized surges in electronics and non-ferrous metals. Yet the single-month slowdown from July's 11.2 percent pace down to August's 4.2 percent indicates that producers are absorbing higher operational costs while slashing prices to clear stagnant inventory.
The core tension stems from an asymmetrical recovery. External demand remains a reliable pressure valve for specific export-oriented sectors, particularly semiconductors, specialized machinery, and green technology components. International markets continue to absorb these goods, keeping factory floors humming across coastal provinces. At home, however, consumer confidence remains subdued, underscored by a sharp pullback in retail spending categories such as automobiles and discretionary goods. When factories scale up output to capture global market share, they generate domestic oversupply that forces aggressive price discounting. Margins evaporate not because factories are idle, but because they are selling more units for less cash return.
Consider a hypothetical mid-tier industrial component supplier in Jiangsu province. Operating under traditional volume-incentivized targets, the plant expands shifts to increase monthly output of mechanical seals by fifteen percent. Externally, overseas buyers demand price concessions due to fierce international competition. Domestically, local manufacturing clients delay payments and demand lower procurement costs due to their own tight cash flows. The factory posts higher volume metrics on paper, but its net margin shrinks drastically. Aggregate output climbs, yet corporate earnings flatten.
This dynamic explains why industrial value-added metrics frequently diverge from corporate profit realization. Policymakers face a complicated balancing act. Directing more fiscal capital toward supply-side expansion risks exacerbating the very overcapacity driving down producer prices. Conversely, allowing market forces to purge inefficient enterprises risks triggering employment shocks across heavy industrial belts.
Addressing this imbalance requires a fundamental shift in capital allocation away from pure volume manufacturing toward household income support and structural domestic consumption stimulation. Until domestic purchasing power catches up with factory gate capacity, profit growth will likely remain vulnerable to external trade friction and margin compression. The August data serves as an unmistakable warning that physical output without matching domestic monetary velocity is a dead end.